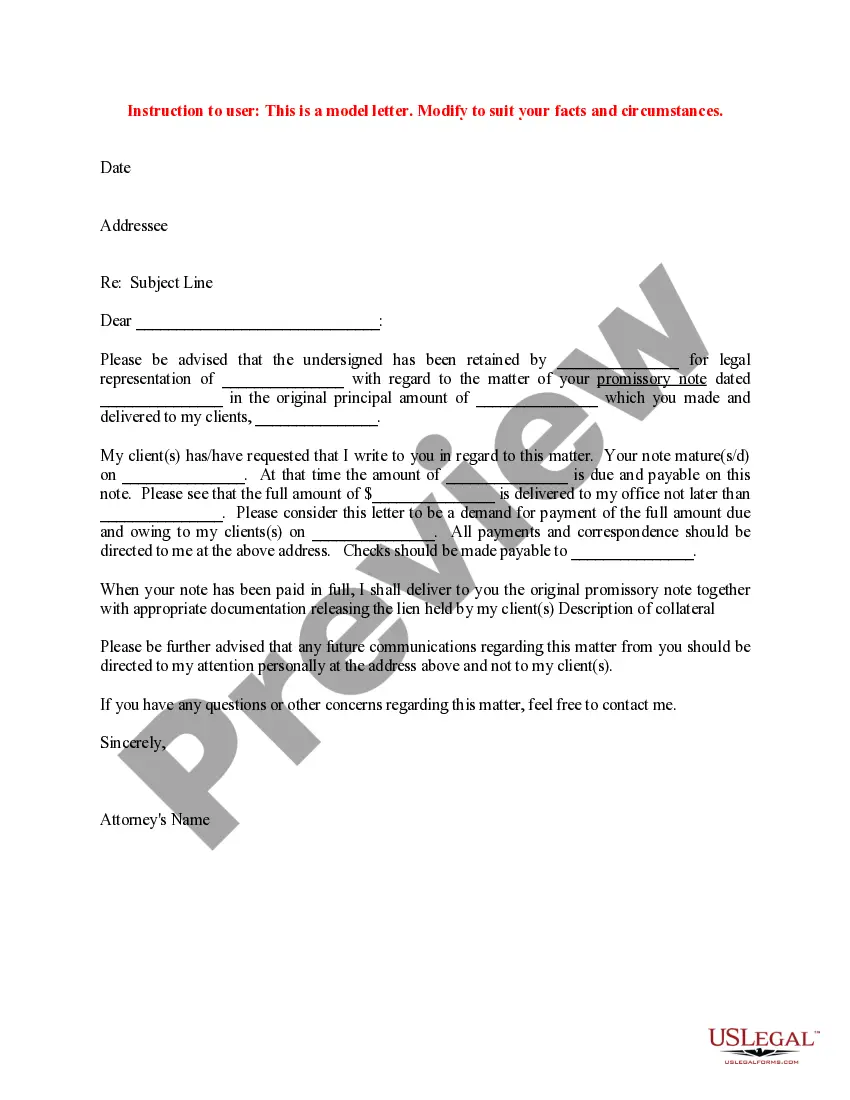
Virginia Demand Letter - Repayment of Promissory Note
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
How to fill out Demand Letter - Repayment Of Promissory Note?
It is feasible to dedicate hours on the internet searching for the approved document template that aligns with the state and federal requirements you seek.
US Legal Forms provides a vast array of legal documents that are reviewed by experts.
You can readily obtain or create the Virginia Demand Letter - Repayment of Promissory Note through your service.
To find an additional version of the form, use the Search field to locate the template that suits your needs and requirements.
- If you already possess a US Legal Forms account, you may Log In and then click the Acquire button.
- Subsequently, you may complete, edit, print, or sign the Virginia Demand Letter - Repayment of Promissory Note.
- Every legal document template you acquire is yours permanently.
- To obtain an additional copy of the purchased form, navigate to the My documents section and click the corresponding button.
- If you are using the US Legal Forms website for the first time, follow the basic instructions provided below.
- First, ensure that you have selected the correct document template for the region/city of your choice.
- Check the form description to verify that you have chosen the proper document.
Form popularity
FAQ
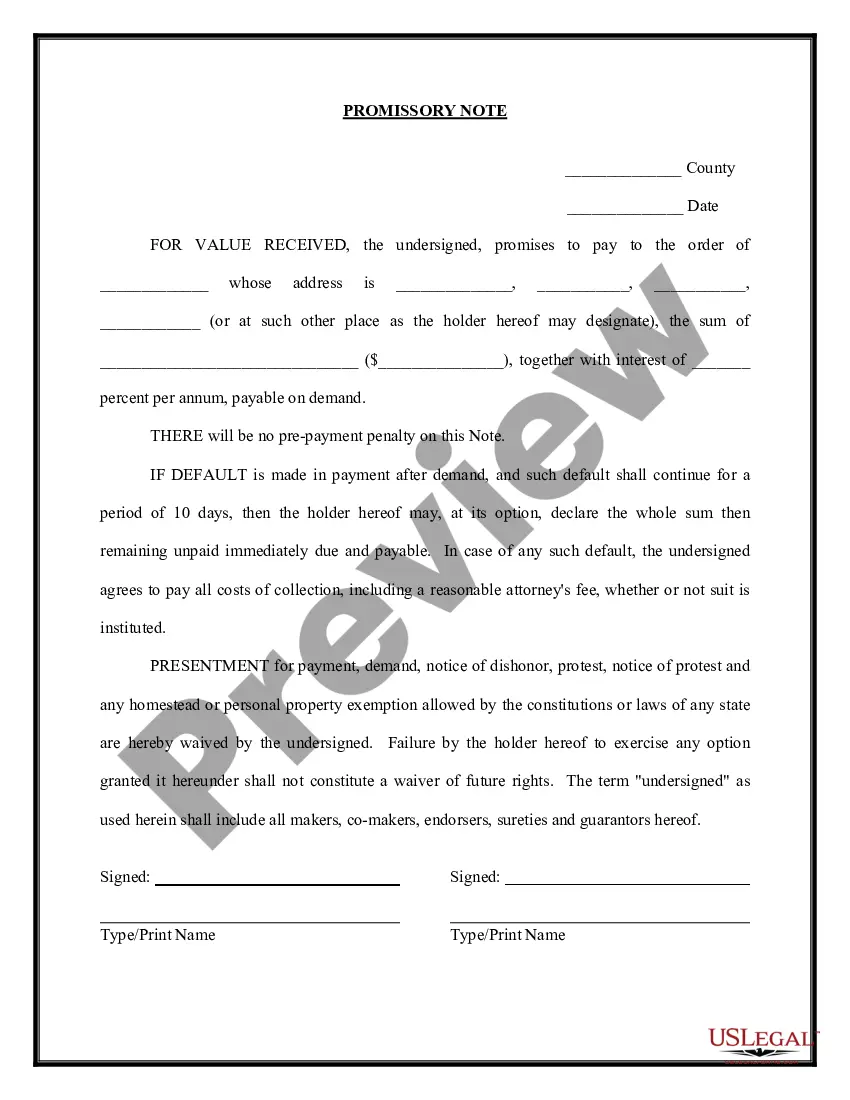
The debt owed on a promissory note either can be paid off, or the noteholder can forgive the debt even if it has not been fully paid. In either case, a release of promissory note needs to be signed by the noteholder.
A promissory note payable on demand is a way to get repaid when you loan money to someone. It is a document that states the terms of the loan and includes the payable on demand notation on it. This means that you can demand full payment of the loan at any time you deem necessary.
The lender can file a civil suit for recovering the money he owed through promissory note or loan agreement. He can do so under Order 37 of CPC which allows the lender to file a summary suit. He can file this suit in any high court, City Civil Court, Magistrate Court, Small Causes Court.
Promissory notes may also be referred to as an IOU, a loan agreement, or just a note. It's a legal lending document that says the borrower promises to repay to the lender a certain amount of money in a certain time frame. This kind of document is legally enforceable and creates a legal obligation to repay the loan.
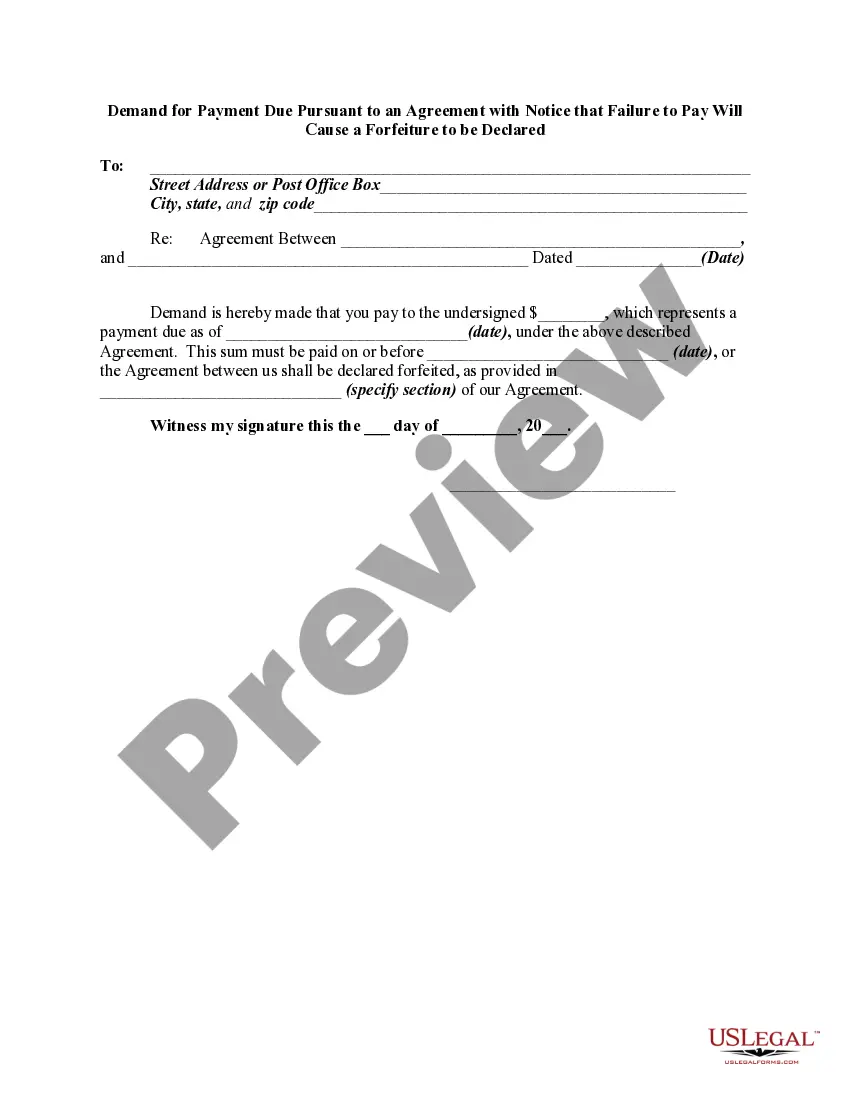
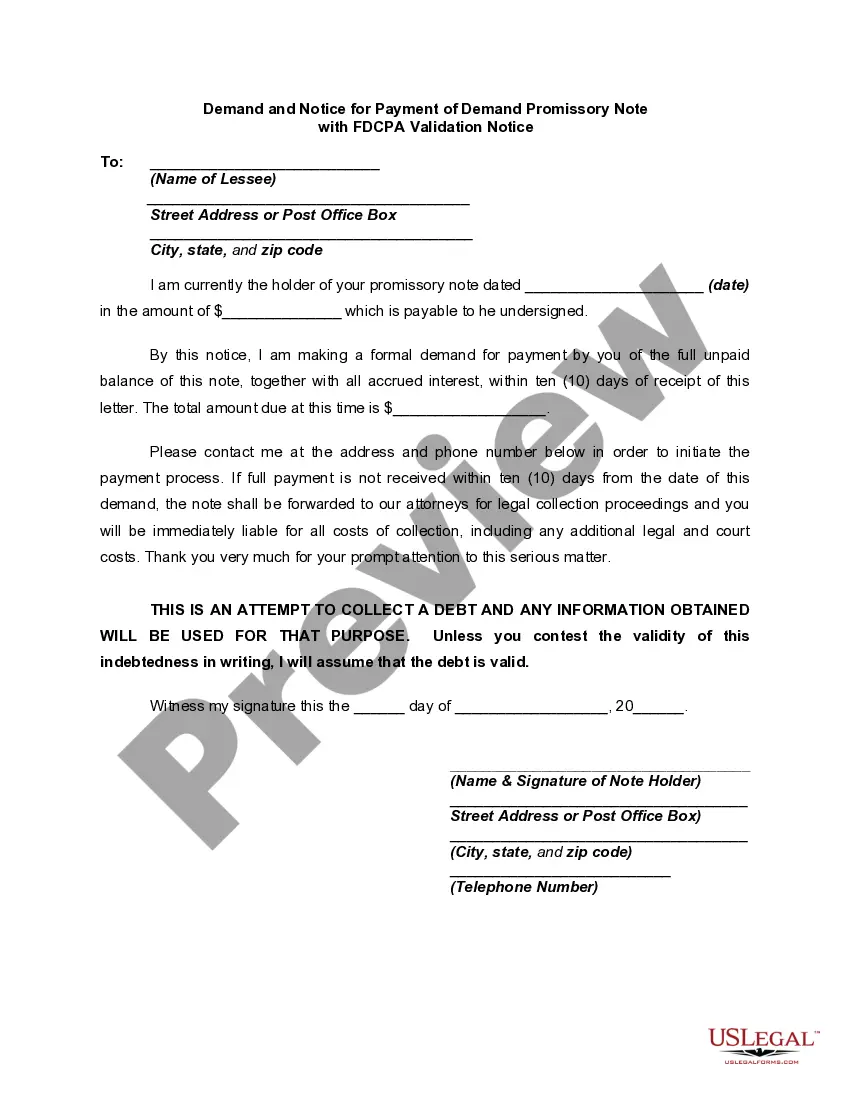
To collect on a demand promissory note, you will need to send a demand for payment letter to the lender. This lets the lender know that you want the loan paid back now and that the repayment period is ending. This demand letter should include the following: The date of the letter.
Promissory note is a written promise to pay a debt. It is a financial instrument, in which one party (maker or issuer) promises in writing to pay a determinate sum of money to the other (the payee), either at a fixed, determinable future time or on demand of the payee subject to specific terms.
What happens when a promissory note is not paid? Promissory notes are legally binding contracts. That means when you don't pay back your loan, you could lose your collateral. If there's no collateral to secure the loan, the lender on the promissory note can take the borrower to court seeking repayment.
What Happens When a Promissory Note Is Not Paid? Promissory notes are legally binding documents. Someone who fails to repay a loan detailed in a promissory note can lose an asset that secures the loan, such as a home, or face other actions.
The lender holds the promissory note while the loan is being repaid. Then the note is marked as paid. It's returned to the borrower when the loan is satisfied.